"/><stop offset="1" stop-color="rgba(255, 255, 255, 0.6)"/></linearGradient><linearGradient id="qavy54DcU-3748361077-linear-gradient" x1="0.49748743718592964" x2="0.5025125628140703" y1="1" y2="0"><stop offset="0" stop-color="rgba(255, 255, 255, 0.6)"/><stop offset="0.5" stop-color="rgb(255, 255, 255)"/><stop offset="1" stop-color="rgb(255, 255, 255)"/></linearGradient></defs><path d="M 15.754 9.25 C 17.821 9.25 19.663 10.217 20.849 11.72 C 21.602 8.508 23.24 5.631 25.49 3.362 C 22.807 1.256 19.426 0 15.754 0 C 7.051 0 0 7.042 0 15.725 C 0 24.408 7.051 31.45 15.754 31.45 C 17.366 31.45 18.921 31.207 20.388 30.759 L 20.388 20.255 C 19.169 21.501 17.498 22.202 15.754 22.2 C 12.169 22.2 9.268 19.302 9.268 15.725 C 9.268 12.148 12.172 9.25 15.754 9.25 Z" fill="rgba(255, 255, 255, 0.6)" height="31.450000000000003px" id="GdGhEU89V" width="25.490121951219518px"/><g d="M 5.095 27.408 C 6.224 28.423 7.614 29.279 9.002 29.938 C 11.048 30.907 13.335 31.45 15.751 31.45 C 17.364 31.45 18.919 31.207 20.383 30.759 L 20.383 20.255 C 19.206 21.455 17.566 22.2 15.751 22.2 C 12.167 22.2 9.264 19.302 9.264 15.725 L 5.095 15.725 Z M 25.488 3.362 C 23.238 5.631 21.6 8.508 20.847 11.72 C 19.66 10.217 17.821 9.25 15.754 9.25 C 12.169 9.25 9.266 12.15 9.266 15.725 L 0 15.725 C 0 7.042 7.049 0 15.751 0 C 19.424 0 22.805 1.256 25.485 3.362 Z M 0 37 L 0 15.494 L 9.268 15.494 L 9.268 27.75 C 9.268 32.858 5.118 37 0 37 Z" fill="transparent" height="36.99999866485596px" id="HmTq7bfqA" transform="translate(22.246 0)" width="25.487804878048752px"><path d="M 0 11.683 C 1.128 12.698 2.519 13.554 3.907 14.213 C 5.953 15.182 8.24 15.725 10.656 15.725 C 12.269 15.725 13.824 15.482 15.288 15.034 L 15.288 4.53 C 14.111 5.73 12.47 6.475 10.656 6.475 C 7.072 6.475 4.168 3.577 4.168 0 L 0 0 Z" fill="rgba(255, 255, 255, 0.6)" height="15.725px" id="hPupmQlUs" transform="translate(5.095 15.725)" width="15.288048780487806px"/><path d="M 25.488 3.362 C 23.238 5.631 21.6 8.508 20.847 11.72 C 19.66 10.217 17.821 9.25 15.754 9.25 C 12.169 9.25 9.266 12.15 9.266 15.725 L 0 15.725 C 0 7.042 7.049 0 15.751 0 C 19.424 0 22.805 1.256 25.485 3.362 Z" fill="url(%23NllbiafvP-3748361077-linear-gradient)" height="15.725000000000001px" id="NllbiafvP" transform="translate(0 0)" width="25.487804878048774px"/><path d="M 0 21.506 L 0 0 L 9.268 0 L 9.268 12.256 C 9.268 17.365 5.118 21.506 0 21.506 Z" fill="rgb(255, 255, 255)" height="21.50625px" id="Z3__vkUos" transform="translate(0 15.494)" width="9.268292682926823px"/></g><g d="M 15.756 0 C 7.053 0 0 7.042 0 15.725 C 0 24.408 7.053 31.45 15.756 31.45 C 24.459 31.45 31.512 24.411 31.512 15.725 C 31.512 7.039 24.457 0 15.756 0 Z M 15.756 22.2 C 12.172 22.2 9.268 19.302 9.268 15.725 C 9.268 12.148 12.172 9.25 15.756 9.25 C 19.341 9.25 22.244 12.15 22.244 15.725 C 22.244 19.3 19.338 22.2 15.756 22.2 Z M 0 15.725 L 9.268 15.725 L 9.268 27.801 C 9.268 32.879 5.137 37 0.051 37 L 0 37 Z" fill="transparent" height="37.00000038146973px" id="NvYsR5b0f" transform="translate(44.488 0)" width="31.512195121951223px"><path d="M 15.756 0 C 7.053 0 0 7.042 0 15.725 C 0 24.408 7.053 31.45 15.756 31.45 C 24.459 31.45 31.512 24.411 31.512 15.725 C 31.512 7.039 24.457 0 15.756 0 Z M 15.756 22.2 C 12.172 22.2 9.268 19.302 9.268 15.725 C 9.268 12.148 12.172 9.25 15.756 9.25 C 19.341 9.25 22.244 12.15 22.244 15.725 C 22.244 19.3 19.338 22.2 15.756 22.2 Z" fill="url(%23qavy54DcU-3748361077-linear-gradient)" height="31.450000000000003px" id="qavy54DcU" width="31.512195121951223px"/><path d="M 0 0 L 9.268 0 L 9.268 12.076 C 9.268 17.154 5.137 21.275 0.051 21.275 L 0 21.275 Z" fill="rgb(255, 255, 255)" height="21.275000000000006px" id="vmYvESJ7u" transform="translate(0 15.725)" width="9.268292682926827px"/></g></svg>)
How Brenger takes the risk out of paying for large-item deliveries with OPP Escrow
Brenger partnered with OPP for PSD2-compliant payments and Escrow, so the money for a delivery that has not happened yet is no longer a risk for the platform or its customers.
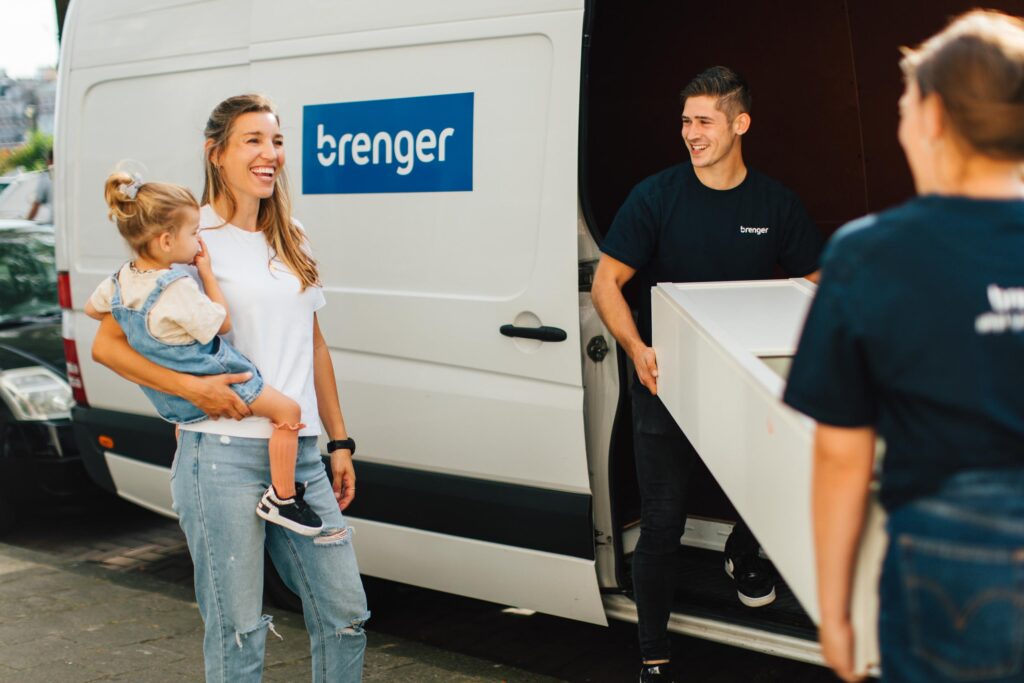
OPP and Brenger partnered to take the risk out of paying for a delivery before it happens: PSD2-compliant payments, with OPP Escrow holding the money until the job is done.
Buying a cabinet on a marketplace is the easy part. Getting it home is not. Brenger, a platform for the smart transportation of large items, built its business on exactly that gap, and by 2021 the payments underneath it had become the constraint. Brenger came to OPP for a PSD2-compliant way to take payment, and OPP added its Escrow solution on top, so that the money sitting in a delivery that has not happened yet is not a risk either side has to carry.
The partnership: taking the risk out of large-item deliveries
Brenger and OPP work together on the payments behind every delivery on the platform. Brenger’s users are typically people who have bought something bulky through a marketplace, a cabinet on Marktplaats or Facebook Marketplace for example, and need it delivered. Founded in 2016 and led by founder Wisse Koedam, Brenger has grown quickly and wants to take its service into Germany.
The challenge: a payment set-up that could not keep up
Since it was founded in 2016, Brenger had worked with the same Dutch payment service provider. That arrangement was chosen when the company was much smaller, and as the platform grew it began to show its limits.
The sharpest issue was regulatory. PSD2 changed what platforms handling third-party money are required to do, and Brenger needed a way to take payment that met that standard rather than working around it. Becoming a payment institution itself, and carrying the compliance weight that comes with it, was not where Brenger wanted to spend its engineering time.
Behind the compliance question sat a trust question. On Brenger, a customer pays for a delivery before it has happened. Without a neutral party holding those funds until the job is done, the financial risk of that gap sits with the platform and with its customers.
“We are growing fast and noticed that our needs for handling payments on our platform were changing. In particular, facilitating a secure and PSD2-worthy way of paying was a valid reason to look for another payment provider.”
Wisse Koedam, Founder of Brenger
Our solution: PSD2-compliant payments and Escrow
Brenger spoke to local providers and to international ones before choosing OPP. Two things decided it.
The first was the licence. OPP holds a licence from De Nederlandsche Bank to execute PSD2 payments, so Brenger did not have to become a payment institution to stay on the right side of the regulation. That regulatory weight sits with OPP instead.
The second was Escrow. OPP had already built its own escrow solution for Marktplaats, called Gelijk Oversteken, and it is technology OPP builds and manages itself rather than buying in. On Brenger it means a customer’s payment is held securely and released once the terms of the deal have been met, so neither side is exposed while a delivery is still in progress.
“Online Payment Platform understands the world we operate in and has an impressive track record with innovative solutions that it builds and manages itself. This makes them an attractive partner for us.”
Wisse Koedam, Founder of Brenger
OPP’s presence in Germany mattered too. Brenger’s ambitions run past the Dutch border, and OPP, with an office in Berlin, can support that expansion and share what it learned entering the German market, where it has worked with eBay Kleinanzeigen.
The impact: no financial risk for Brenger or its customers
With PSD2 and Escrow in place, the financial risk comes out of the transaction, for Brenger and for the people using the platform. Brenger expects that to show up in how many marketplace buyers pick it to deliver what they have just bought.
“Users who have bought a cabinet through Marktplaats or Facebook Marketplace and want to have it delivered through us can now pay even more securely and easily. Thanks to PSD2 and Escrow, there are no financial risks involved for us or our customers. So now that we have payments set up with Online Payment Platform, we expect even more people who buy big stuff through a marketplace to use the Brenger delivery service.”
Wisse Koedam, Founder of Brenger
From OPP’s side:
“Brenger is a very promising platform that I also enjoy using myself. I think it’s great to be able to contribute with our services and expertise to the growth in the Netherlands, and in time beyond, by making payments easier and safer for all users.”
Richard Straver, Founder of Online Payment Platform
What this means for you: why delivery and marketplace platforms need PSD2-compliant payments
If you run a platform where customers pay for something that will be delivered or completed later, Brenger’s problem is probably one you recognise: a payment set-up chosen when the company was smaller, and a compliance bar that has risen since. Payments sit in the middle of every transaction, so the way they are handled decides how much risk each side carries.
A licensed payment partner and escrow address both at once. The regulatory weight sits with the provider instead of your product team, and funds are held until the deal is actually done.
Want to see how PSD2-compliant payments and Escrow could work for your platform? Get in touch to learn more.
Frequently asked questions
What is OPP Escrow?
Escrow holds a buyer’s payment securely instead of passing it straight to the other party, and releases it once the terms of the deal have been met. OPP built its own escrow solution for Marktplaats, called Gelijk Oversteken, and implemented an Escrow solution for Brenger.
When should a growing platform switch payment provider?
Brenger switched when it had outgrown the provider it chose at launch in 2016. As the platform grew, it needed a secure, PSD2-compliant way of taking payment, and escrow to take the risk out of paying for a delivery before it happens.
What does a PSD2 licence mean for a platform?
Platforms that process third-party funds fall within the scope of PSD2. Working with a provider that holds a licence from De Nederlandsche Bank to execute PSD2 payments means the platform does not have to become a payment institution itself to stay compliant.
Can OPP support platforms expanding into other European markets?
Yes. OPP works with platforms across Europe from offices in the Netherlands, Germany, the United Kingdom and Spain. Its experience in Germany, where it worked with eBay Kleinanzeigen, was one of the reasons Brenger chose OPP.
Services used

Hyunji Kim
Content & PR Lead