"/><stop offset="1" stop-color="rgba(255, 255, 255, 0.6)"/></linearGradient><linearGradient id="qavy54DcU-3748361077-linear-gradient" x1="0.49748743718592964" x2="0.5025125628140703" y1="1" y2="0"><stop offset="0" stop-color="rgba(255, 255, 255, 0.6)"/><stop offset="0.5" stop-color="rgb(255, 255, 255)"/><stop offset="1" stop-color="rgb(255, 255, 255)"/></linearGradient></defs><path d="M 15.754 9.25 C 17.821 9.25 19.663 10.217 20.849 11.72 C 21.602 8.508 23.24 5.631 25.49 3.362 C 22.807 1.256 19.426 0 15.754 0 C 7.051 0 0 7.042 0 15.725 C 0 24.408 7.051 31.45 15.754 31.45 C 17.366 31.45 18.921 31.207 20.388 30.759 L 20.388 20.255 C 19.169 21.501 17.498 22.202 15.754 22.2 C 12.169 22.2 9.268 19.302 9.268 15.725 C 9.268 12.148 12.172 9.25 15.754 9.25 Z" fill="rgba(255, 255, 255, 0.6)" height="31.450000000000003px" id="GdGhEU89V" width="25.490121951219518px"/><g d="M 5.095 27.408 C 6.224 28.423 7.614 29.279 9.002 29.938 C 11.048 30.907 13.335 31.45 15.751 31.45 C 17.364 31.45 18.919 31.207 20.383 30.759 L 20.383 20.255 C 19.206 21.455 17.566 22.2 15.751 22.2 C 12.167 22.2 9.264 19.302 9.264 15.725 L 5.095 15.725 Z M 25.488 3.362 C 23.238 5.631 21.6 8.508 20.847 11.72 C 19.66 10.217 17.821 9.25 15.754 9.25 C 12.169 9.25 9.266 12.15 9.266 15.725 L 0 15.725 C 0 7.042 7.049 0 15.751 0 C 19.424 0 22.805 1.256 25.485 3.362 Z M 0 37 L 0 15.494 L 9.268 15.494 L 9.268 27.75 C 9.268 32.858 5.118 37 0 37 Z" fill="transparent" height="36.99999866485596px" id="HmTq7bfqA" transform="translate(22.246 0)" width="25.487804878048752px"><path d="M 0 11.683 C 1.128 12.698 2.519 13.554 3.907 14.213 C 5.953 15.182 8.24 15.725 10.656 15.725 C 12.269 15.725 13.824 15.482 15.288 15.034 L 15.288 4.53 C 14.111 5.73 12.47 6.475 10.656 6.475 C 7.072 6.475 4.168 3.577 4.168 0 L 0 0 Z" fill="rgba(255, 255, 255, 0.6)" height="15.725px" id="hPupmQlUs" transform="translate(5.095 15.725)" width="15.288048780487806px"/><path d="M 25.488 3.362 C 23.238 5.631 21.6 8.508 20.847 11.72 C 19.66 10.217 17.821 9.25 15.754 9.25 C 12.169 9.25 9.266 12.15 9.266 15.725 L 0 15.725 C 0 7.042 7.049 0 15.751 0 C 19.424 0 22.805 1.256 25.485 3.362 Z" fill="url(%23NllbiafvP-3748361077-linear-gradient)" height="15.725000000000001px" id="NllbiafvP" transform="translate(0 0)" width="25.487804878048774px"/><path d="M 0 21.506 L 0 0 L 9.268 0 L 9.268 12.256 C 9.268 17.365 5.118 21.506 0 21.506 Z" fill="rgb(255, 255, 255)" height="21.50625px" id="Z3__vkUos" transform="translate(0 15.494)" width="9.268292682926823px"/></g><g d="M 15.756 0 C 7.053 0 0 7.042 0 15.725 C 0 24.408 7.053 31.45 15.756 31.45 C 24.459 31.45 31.512 24.411 31.512 15.725 C 31.512 7.039 24.457 0 15.756 0 Z M 15.756 22.2 C 12.172 22.2 9.268 19.302 9.268 15.725 C 9.268 12.148 12.172 9.25 15.756 9.25 C 19.341 9.25 22.244 12.15 22.244 15.725 C 22.244 19.3 19.338 22.2 15.756 22.2 Z M 0 15.725 L 9.268 15.725 L 9.268 27.801 C 9.268 32.879 5.137 37 0.051 37 L 0 37 Z" fill="transparent" height="37.00000038146973px" id="NvYsR5b0f" transform="translate(44.488 0)" width="31.512195121951223px"><path d="M 15.756 0 C 7.053 0 0 7.042 0 15.725 C 0 24.408 7.053 31.45 15.756 31.45 C 24.459 31.45 31.512 24.411 31.512 15.725 C 31.512 7.039 24.457 0 15.756 0 Z M 15.756 22.2 C 12.172 22.2 9.268 19.302 9.268 15.725 C 9.268 12.148 12.172 9.25 15.756 9.25 C 19.341 9.25 22.244 12.15 22.244 15.725 C 22.244 19.3 19.338 22.2 15.756 22.2 Z" fill="url(%23qavy54DcU-3748361077-linear-gradient)" height="31.450000000000003px" id="qavy54DcU" width="31.512195121951223px"/><path d="M 0 0 L 9.268 0 L 9.268 12.076 C 9.268 17.154 5.137 21.275 0.051 21.275 L 0 21.275 Z" fill="rgb(255, 255, 255)" height="21.275000000000006px" id="vmYvESJ7u" transform="translate(0 15.725)" width="9.268292682926827px"/></g></svg>)
How UWassistent (now Hups) offers simple, safe payments for the elderly with OPP
UWassistent, now Hups, connects elderly people with local care providers. OPP handles the payments between them as an independent third party. Clients pay the way they are used to, including by bank transfer and direct debit, and UWassistent sees where every payment stands.

Since 2013, UWassistent has supported elderly people with long-term independent living at home. It is available nationwide and online, but also locally and in person: household help, personal guidance and the smaller jobs around the house, from mowing the lawn to replacing a light bulb, for which you cannot hire a large company.
UWassistent works as a franchise. Local contact persons, independent entrepreneurs who know the social map of their area, arrange the help and match each client with a screened care provider.
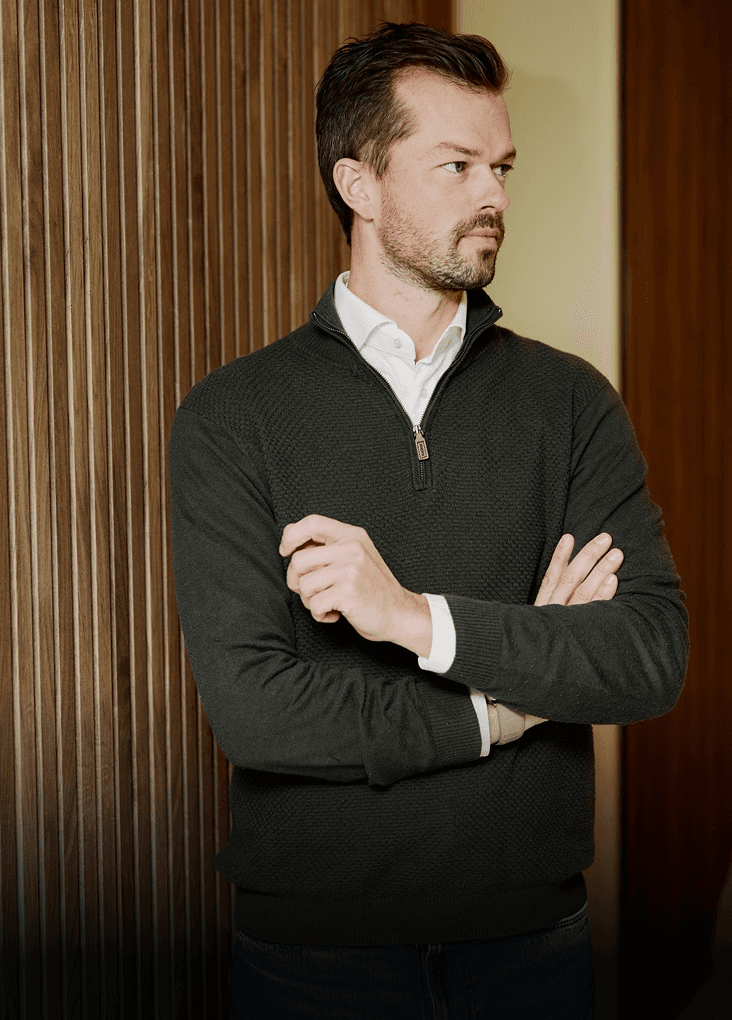
“All care providers are screened for legal obligations, but besides a screening, we look for service providers that really match with these clients. We hold personal meetings with clients and service providers to find out the qualities of the service providers and the wishes of the client.”
Joost Damen, Co-owner of UWassistent
The partnership: safe payments for a vulnerable audience
Payments between a client and a care provider have to be safe and reliable, and with elderly clients that bar is higher than usual. Rather than handle these payments between private individuals itself, UWassistent, which now operates as Hups, wanted a specialised, independent party to sit between client and care provider. OPP took on that role.
OPP runs the payments between these clients and the local care providers who help them. Clients pay the way they’re used to, including by bank transfer and direct debit, while UWassistent follows every payment in OPP’s Partner Interface.
The challenge: a third-party set-up and many ways to pay
UWassistent’s model needed a specific payment set-up: payments between two private individuals, a client and a care provider, with UWassistent as a third party in the middle. This kind of peer-to-peer (P2P) set-up is not something every payment provider offers, and UWassistent found it very difficult to find.
Its audience added a second requirement. Many elderly clients do not pay online with iDEAL or a credit card; they prefer a manual bank transfer or a direct debit. UWassistent needed a provider that could offer all of these methods side by side.
“UWassistent also had other requirements because we mainly work with the elderly. Elderly people have to pay in many different ways, not just with iDEAL or credit card. We needed many different possibilities for payments, including manual transfers and direct debits. Fortunately, Online Payment Platform was one of the few parties able to meet all our requirements.”

Joost Damen, Co-owner of UWassistent
Our solution: P2P payments with OPP Escrow, instant payouts and every familiar payment method
OPP set up payments between clients and care providers with UWassistent as the third party, so the platform never holds the money and never has to act as a payment provider. When a client pays, the money is held by OPP in Escrow, and the care provider is paid through OPP’s instant payouts. Alongside iDEAL and cards, clients can pay by manual bank transfer or direct debit.
OPP’s team thinks along on customised solutions for this audience and, when a payment fails, helps inform UWassistent’s clients about what went wrong.
“We are very satisfied with them. They think along with customised solutions and how we can arrange the best payment solutions for our target group. Communication is also very important; Online Payment Platform helps with informing our clients when something is not working, and that is especially nice for our clients.”
Joost Damen, Co-owner of UWassistent
The impact: faster growth and a more professional platform
Moving payments to OPP saved UWassistent time and, in Joost Damen’s words, gave the platform trust: payments are arranged externally, the system looks flawless, and clients and care providers see a more professional organisation.
“Better insights into money flows and payment automation enabled us to grow faster and realise more volumes. Offering P2P payments in combination with many different payment methods provides the perfect solution for our target group.”
Joost Damen, Co-owner of UWassistent
OPP’s Partner Interface gives UWassistent insight into how customers pay, which payments are completed, pending or on hold, and how much is still to be deposited. During the Covid-19 period, when personal services were held back, that overview helped the platform keep running as care providers and clients worked out safe ways to continue.
UWassistent has since merged with Mantelaar and Hlprs and continues as Hups, and the payments between its clients and helpers still run through OPP.
“This gives us better insights on how customers pay, which payments are completed or have not been completed, which payments are still on hold, and the amount that still needs to be deposited at UWassistent. This is an extremely valuable tool for UWassistent.”
Joost Damen, Co-owner of UWassistent
What this means for you: why service platforms need P2P payments with a third party
If you run a service platform where private individuals pay other private individuals, and your audience does not all pay the same way, UWassistent’s two requirements are yours: a licensed third party in the middle, and every payment method your users expect, from iDEAL to direct debit and bank transfer.
With OPP, that third party holds the money in Escrow, pays your providers out, and gives you one dashboard to follow it all.
Want to see how OPP could set up P2P payments for your platform? Get in touch to learn more.
Frequently asked questions
What are P2P payments with a third party?
P2P (peer-to-peer) payments are payments between two private individuals, in this case a client and a care provider. With a third party in between, the platform arranges the service but does not hold the money itself: OPP does. UWassistent needed exactly this set-up and found few providers that offered it.
Can clients who do not pay online still pay through the platform?
Yes. Many of UWassistent’s elderly clients prefer a manual bank transfer or a direct debit to iDEAL or a card. OPP offers all of these, so every client can pay the way they are used to.
How does the platform keep track of payments?
In OPP’s Partner Interface, UWassistent sees how customers pay, which payments are completed, pending or on hold, and how much is still to be deposited. UWassistent calls it an extremely valuable tool.
What happens when a client’s payment fails?
OPP helps UWassistent inform its clients when a payment does not go through. For an audience that is not always comfortable with digital payments, that support matters.
What does a care platform gain from outsourcing payments?
For UWassistent, better insight into money flows and automated payments meant it could grow faster and handle more volume, saved a lot of work, and looked more professional to clients and care providers.

Hyunji Kim
Content & PR Lead